In Florida, your own personal injury protection (PIP) coverage does not pay to repair your vehicle. Property damage may be paid by the at-fault driver’s property damage liability coverage, for which Florida requires at least $10,000, or by your own collision coverage subject to its deductible and policy terms. Photograph the damage, get a written estimate and report the claim promptly. See Florida Statutes section 324.022 and the PIP benefits in section 627.736.
Hurt in an Accident? Talk to a Lawyer Today.
Consultations are free. Call (813) 553-5648 or start your free case review online.
If the crash also caused injuries, see our Tampa car accident lawyer page for information about medical documentation, liability and coverage.
Immediately After the Accident: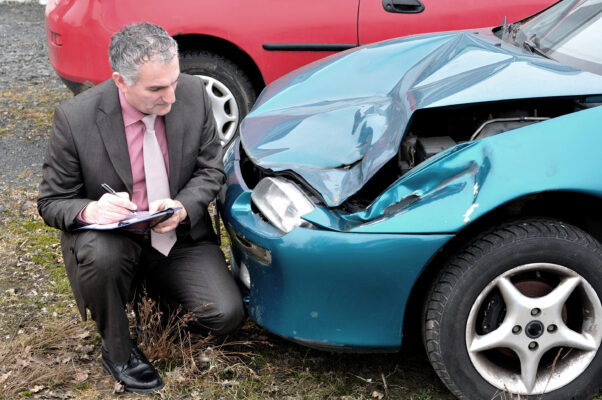
The first priority after a car accident is to ensure your safety and well-being. Once you have ensured your immediate safety, follow these steps:
- Contact Law Enforcement: It is essential to report the accident to law enforcement authorities, especially if there are injuries or extensive property damage. This step will also help in creating an official record of the incident.
- Exchange Information: Exchange contact and insurance information with the other parties involved in the accident. Obtain details such as names, phone numbers, addresses, driver’s license numbers, and insurance policy information.
- Document the Scene: Take photos or videos of the accident scene, including the damage to your vehicle and any other involved vehicles. These visuals will serve as valuable evidence during the claims process.
Insurance Coverage and Requirements:
Understanding the insurance coverage and requirements in Florida is crucial when dealing with property damage claims. Here are the key points to keep in mind:
- No-Fault Insurance: Florida follows a no-fault insurance system. This means that regardless of who is at fault, your own insurance company is responsible for covering your property damage up to the limits of your policy.
- Minimum Coverage Requirements: Florida law requires drivers to carry a minimum of $10,000 in property damage liability (PDL) coverage. This coverage applies when you are at fault and cause damage to another person’s property.
- Collision Coverage: Collision coverage is optional but highly recommended. It covers the damage to your vehicle regardless of fault, subject to your deductible.
- Deductibles: Review your insurance policy to determine the deductible amount you must pay before your coverage kicks in. This amount will vary depending on your policy.
Filing a Property Damage Claim:
To initiate the property damage claim process, follow these steps:
- Contact Your Insurance Company: Notify your insurance company about the accident and provide them with the necessary information, including the details of the accident and the other parties involved. Follow their instructions for filing a property damage claim.
- Obtain Estimates: Get multiple repair estimates from reputable auto repair shops to determine the extent of the damage and associated repair costs. Share these estimates with your insurance company.
- Assessing the Vehicle: Your insurance company may send an adjuster to inspect the vehicle and assess the damage. They will determine whether the vehicle is repairable or a total loss.
- Negotiating the Settlement: Once the assessment is complete, the insurance company will provide a settlement offer based on the repair costs and the vehicle’s value. Review the offer carefully and negotiate if necessary.
Seeking Legal Assistance:
In some cases, dealing with insurance companies can be complex, especially if your claim is denied, or you believe the settlement offer is insufficient. In such situations, it is advisable to seek legal assistance. An experienced personal injury attorney can help you navigate the legal complexities, negotiate with the insurance company on your behalf, and ensure you receive fair compensation for your property damage.
Disputes and Resolving Issues:
Sometimes, disputes may arise during the property damage claims process. Here’s how to handle common issues:
- Denial of Claim: If your insurance company denies your claim, review the denial letter carefully to understand the reasons. You have the right to appeal the decision and provide additional evidence to support your claim. Consider seeking legal guidance to navigate the appeals process effectively.
- Insufficient Settlement Offer: If you believe the settlement offer is insufficient to cover your property damage, gather evidence such as repair estimates, receipts, and photographs to demonstrate the actual cost of repairs. Present this evidence to your insurance company and negotiate for a fair settlement. An attorney can help you negotiate effectively and advocate for your rights.
- Diminished Value Claims: In some cases, even after repairs, a vehicle may have diminished value due to the accident history. Florida law allows for claims seeking compensation for the diminished value of your vehicle. Consult with an attorney experienced in handling diminished value claims to understand your options and pursue the appropriate compensation.
Handling Property Damage Claims Without Insurance:
In situations where the at-fault party does not have insurance or is underinsured, the property damage claim process can be more complicated. Consider the following steps:
- Uninsured/Underinsured Motorist Coverage: If you have uninsured or underinsured motorist coverage as part of your policy, you can file a claim with your insurance company. This coverage protects you in case of accidents involving uninsured or underinsured drivers.
- Small Claims Court: If the damage is minor and within the small claims court limit, you can file a lawsuit against the at-fault party. Small claims court provides a relatively quick and affordable way to seek compensation for property damage.
- Legal Assistance: If you encounter difficulties in pursuing a property damage claim without insurance coverage, it is advisable to consult with a knowledgeable attorney. They can guide you through the legal process, evaluate your options, and help you navigate the complexities of the situation.
The Importance of Timeliness:
It’s crucial to remember that timing plays a significant role in property damage claims. Take these time-sensitive factors into consideration
- Prompt Reporting: Report the accident and file your property damage claim with your insurance company as soon as possible. Prompt reporting ensures that your claim is processed efficiently and that any applicable deadlines are met.
- Statute of Limitations: In Florida, there is a statute of limitations, which is the time limit for filing a lawsuit. For property damage claims, the statute of limitations is typically four years from the date of the accident. However, it is advisable to consult with an attorney to understand the specific time limits that apply to your case.
Navigating property damage claims after a car accident in Florida can be challenging, but being well-informed and prepared significantly increases your chances of a successful claim. Remember to document the accident scene, understand your insurance coverage, promptly file a claim, and consider seeking legal assistance when needed. By following these steps, you can protect your rights and recover the compensation you deserve for your property damage.
If you have questions or need expert guidance in handling your property damage claim, don’t hesitate to contact our experienced team at Serrano Law. Our dedicated attorneys are here to provide personalized support and help you navigate the complex legal process.
Dealing with property damage claims after a car accident in Florida requires knowledge of the process and adherence to the state’s insurance requirements. By following the steps outlined in this guide and seeking legal assistance when necessary, you can effectively handle your property damage claim and ensure you receive fair compensation for your losses. Remember, being informed and proactive is the key to protecting your rights and securing a favorable outcome.